Closing gift guide
Are closing gifts tax deductible for real estate agents?
Yes, up to $25 per recipient per tax year. Here is what the IRS rule says, what counts toward the $25, the two shortcuts it does not support, and the records to keep.
- Free framing and shipping
- Unlimited changes
- Pay only when you approve

The short answer
Yes. A real estate agent can deduct closing gifts as business gifts, up to $25 per recipient per tax year. The limit comes from section 274(b)(1) of the tax code.
You can spend more than $25. Only the deduction is capped.
The closing gift deduction: $25 per person, per year
IRS Publication 463, chapter 3 puts the limit in one sentence: "You can deduct no more than $25 for business gifts you give directly or indirectly to each person during your tax year." The law behind it is section 274(b)(1) of the tax code, and the figure is unchanged as of the 2025 edition of Publication 463.
The limit is per person per year, not per gift. Give the same client a $60 closing gift in March and a $40 gift in December and you have spent $100 and can deduct $25, not $50.
Spending more than $25 is fine. The rule does not limit what you give. It limits what you deduct. On a $150 gift, $25 is deductible as a gift and the other $125 is not. Our guide on how much to spend on closing gifts covers the budget itself.
This is not tax advice, so check with your CPA before you file.
What counts toward the $25
The price of the gift counts. Some of the costs around it do not.
| Cost | Toward the $25? | Why |
|---|---|---|
| The gift itself | Toward the $25?Yes | WhyThe price you paid for it |
| Engraving on jewelry, packaging, insuring, mailing | Toward the $25?Generally no | WhyIncidental costs, if they do not add substantial value to the gift |
| An extra that makes the gift worth more | Toward the $25?Yes | WhyA cost that adds substantial value is not incidental |
| A second gift to the same client that year | Toward the $25?Yes | WhyOne $25 limit per person per tax year |
| A gift to the client's spouse or family | Toward the $25?Generally yes | WhyTreated as an indirect gift to the client |
| An item of $4 or less with your name imprinted, handed out widely | Toward the $25?No | WhyNot counted as a gift |
The test for incidental costs is one sentence in Publication 463: "A cost is incidental only if it doesn't add substantial value to the gift."
Closing gift guide
The rule does not limit what you give. It limits what you deduct.
Putting your logo on a gift does not make it advertising
Publication 463 has an exception that agents stretch. An item is not treated as a gift if it costs $4 or less, has your name clearly and permanently imprinted on it, and is something you distribute widely. All three have to be true.
The price is part of the test. A $100 basket with your logo on the ribbon is still a $100 gift, and the $25 limit still applies. A $60 cutting board with your name engraved on the back is still a $60 gift. Whether a logo belongs on a gift at all is a separate question, and our guide to personalized closing gifts covers it.
A couple who bought together
Do not assume two buyers means two recipients and $50. Publication 463 says a gift to a member of a client's family "is generally considered to be an indirect gift to the customer." The exception is a family member you have a bona fide, independent business connection with.
Whether a couple who both signed with you fits that exception is a question for your CPA. Ask before you count $50.
What records to keep
For each gift, Publication 463 asks you to keep five things:
- The cost
- The date of the gift
- A description of the gift
- The business reason for giving it
- The business relationship of the person who got it
A receipt usually shows the cost and what you bought. Write the rest down yourself, for example: closing gift, buyer client, sale closed in May.
Whether you may give the gift at all is a different question from whether you can deduct it. Our guide to whether realtors can give closing gifts covers that side.
The math on a house portrait
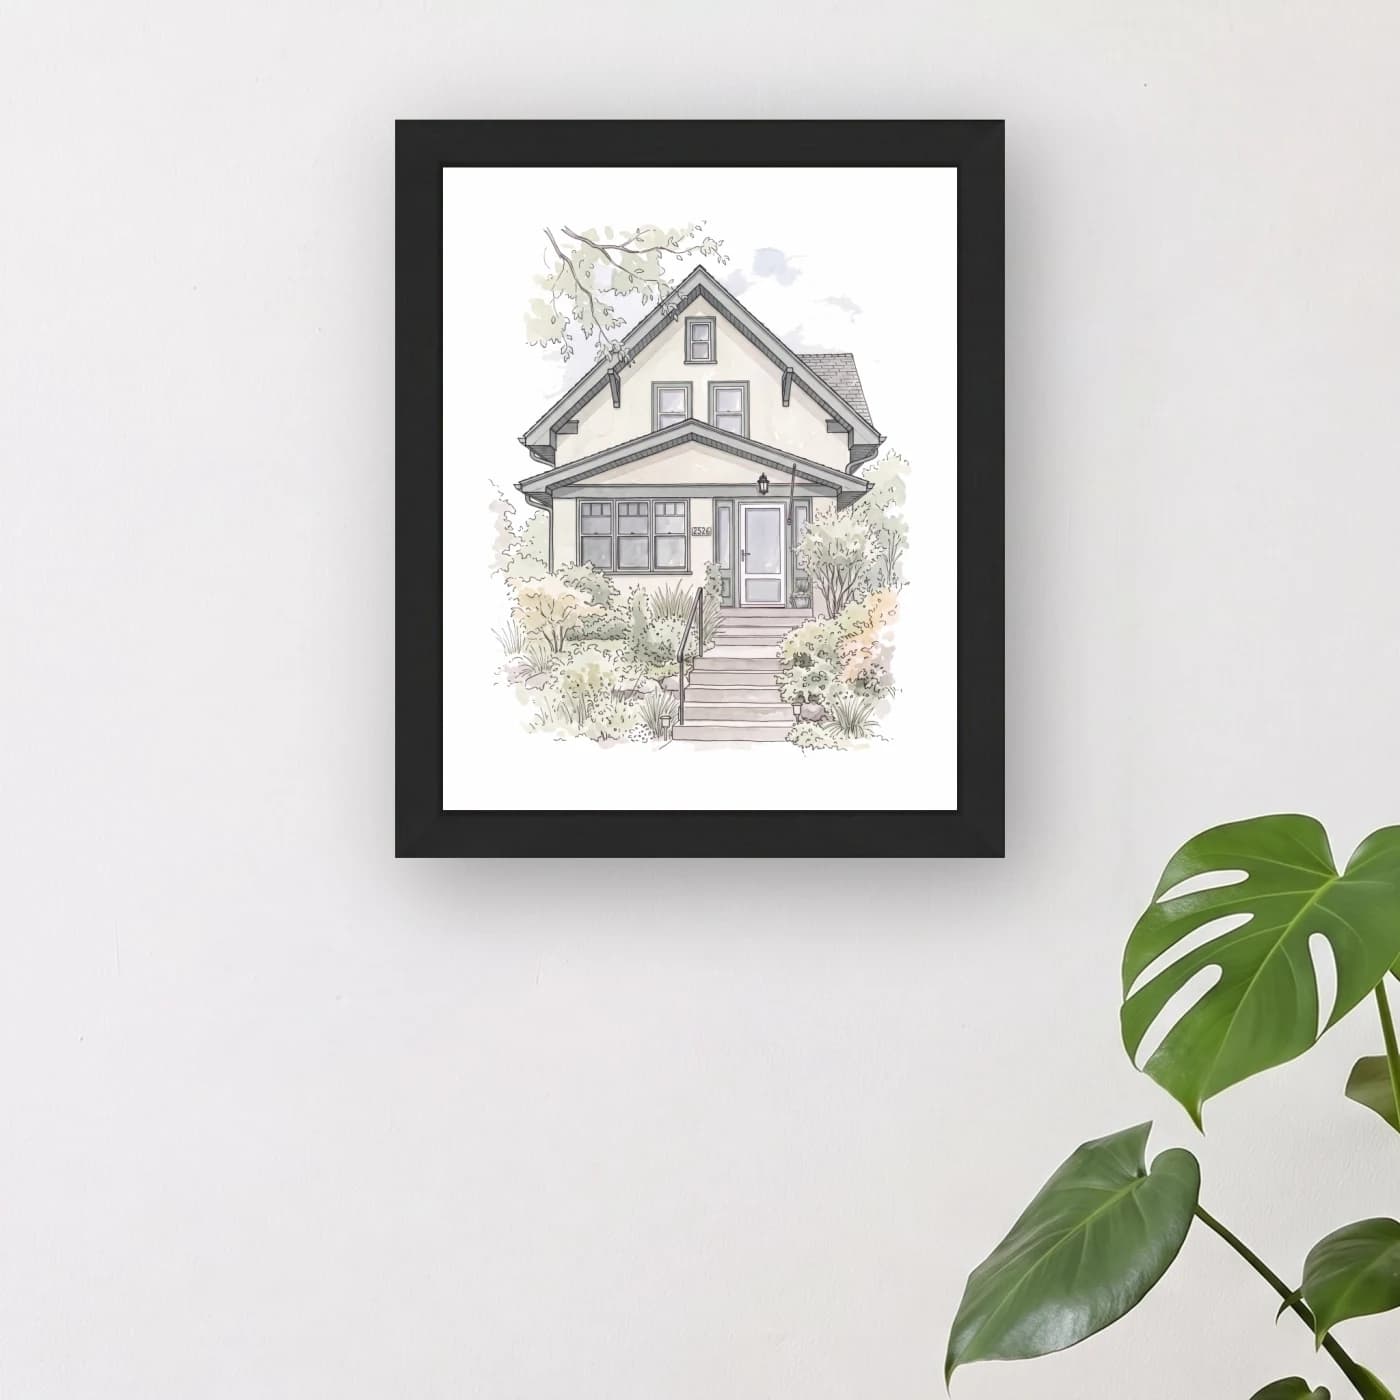
Here is the rule on a real receipt. Doorstep Gifts makes a framed portrait of a client's house from one photo, in ink and watercolor: an 8 × 10 in a black, red oak or white frame, no mat, ready to hang. It costs $79, with free US shipping to you or straight to the client.
Up to $25 of that $79 is deductible as a gift under this rule, and the rest is not. Shipping is already inside our price, so there is no separate mailing cost to set aside as incidental. The frame adds value to the gift, so we would not count it as incidental.
Each portrait is ordered on its own, so every client's gift has its own receipt with the date and the amount. To order one, upload the listing photo you already have. The first proof comes back within two business days, changes are free and unlimited, and you pay only when you approve. The framed portrait arrives five to seven business days after that.
The trade-off: if the write-off is the point, a portrait is the wrong gift. A $25 gift is deductible in full when it is the only one that client gets from you that year, and the part of our price above $25 is not deductible as a gift.
- BlackThe safe pick when you have not seen the inside of the home. Reads modern and disappears on any wall color.
- Red oakWarm, visible grain. The one we would choose for a craftsman, a farmhouse or anywhere with wood floors.
- WhiteFor bright, coastal and new-build interiors, and for kitchens and nurseries.
$79
- Free framing and shipping
- Unlimited changes
- Pay only when you approve
Keep reading
A guide for agents
How much should a realtor spend on a closing gift?Closing gift guide
Can real estate agents give gifts to clients?Closing gifts for real estate agents
Closing gifts for real estate agents that stay on the wall
Everything before you commit.
Can a real estate agent write off closing gifts?
How much can a realtor write off for client gifts?
I gave my buyers a $100 gift card after closing. Can I deduct the $100?
Is the limit different for buyers and sellers?
Is the closing gift limit per closing or per year?
Has the $25 business gift limit gone up?
A complete framed portrait for $79
It's their house. You already know they'll love it.
Upload one photo and pay $79 only when you approve the proof.